Can British citizens buy property in Dubai?
Yes. Dubai permits foreign nationals to purchase freehold property in over 60 designated zones — including Jumeirah Golf Estates, Dubai Marina, Downtown Dubai, Palm Jumeirah and Dubai Hills Estate. There are no nationality restrictions within these freehold zones.
The process is regulated by the Dubai Land Department (DLD) and broadly comparable to buying in the UK: a signed sale agreement, a title deed transfer and a DLD registration complete the transaction. No minimum residency is required to purchase.
What does buying actually cost?
The primary transaction cost is the DLD transfer fee: 4% of the agreed purchase price, paid on completion. On an AED 5 million property (approximately £1.1 million at current exchange rates), that is AED 200,000 — versus up to £263,750 in UK stamp duty on the same value purchased as a second home.
Additional costs include: a DLD registration trustee fee of approximately AED 4,200; agency commission of typically 2% + VAT if using an agent; and mortgage arrangement and valuation fees if buying with finance. Total transaction costs typically land at 5.5–7% of the purchase price.
There is no annual council tax or property tax in Dubai. Service charges — covering building maintenance, landscaping and community facilities — are the main ongoing cost. In Jumeirah Golf Estates these typically run AED 15–25 per square foot per year; in Dubai Marina apartments, AED 12–22 per square foot.
The UAE Golden Visa: residency through property
Buyers who purchase property worth AED 750,000 or more can apply for a two-year renewable UAE investor residence visa. Buyers at AED 2 million or above qualify for the UAE Golden Visa: ten-year renewable residency extended to immediate family, with no minimum days-per-year in-country requirement.
The Golden Visa makes Dubai viable as a primary or secondary residence for buyers who divide their time between the UAE and the UK, without the threat of a residency lapse through absence.
Mortgages for non-resident UK buyers
Non-resident British buyers can obtain UAE mortgages at up to 75% loan-to-value (versus 80% for UAE residents). UAE banks including Emirates NBD, ADCB and Mashreq, alongside international names such as HSBC and Standard Chartered, offer products to UK applicants.
UAE mortgage rates are typically variable, linked to EIBOR. Many British buyers purchase cash, particularly for investment properties, due to the relative simplicity and the dirham's peg to the US dollar reducing currency settlement risk.
UK tax implications — what British buyers must know
The UAE taxes neither capital gains nor rental income. However, UK tax residents remain liable to UK tax on worldwide income and gains — including those arising from Dubai property. Rental income from Dubai property received by a UK tax resident is taxable as UK income at marginal rates (20–45%). Capital gains on Dubai property sold while UK tax resident are subject to UK CGT at 18–24% (residential property rates).
British buyers who formally exit UK tax residency by satisfying the Statutory Residence Test criteria would not be liable for UK CGT on Dubai property gains. Independent advice from a UK-UAE cross-border tax specialist is strongly recommended before completing a purchase.
Communities popular with British buyers
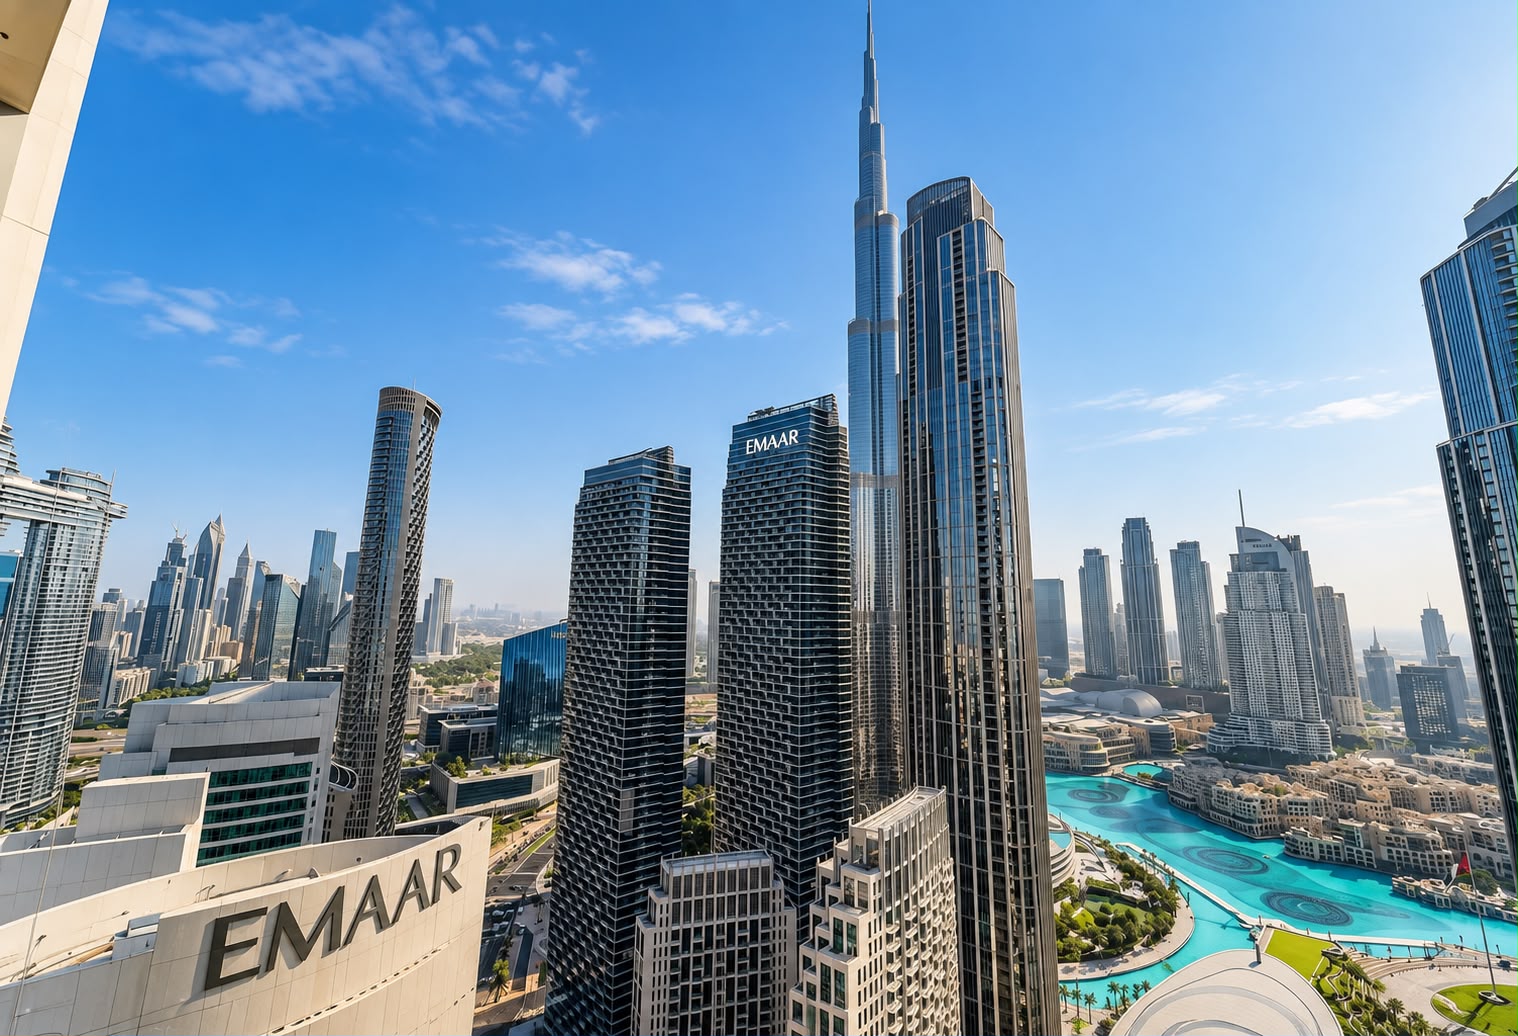
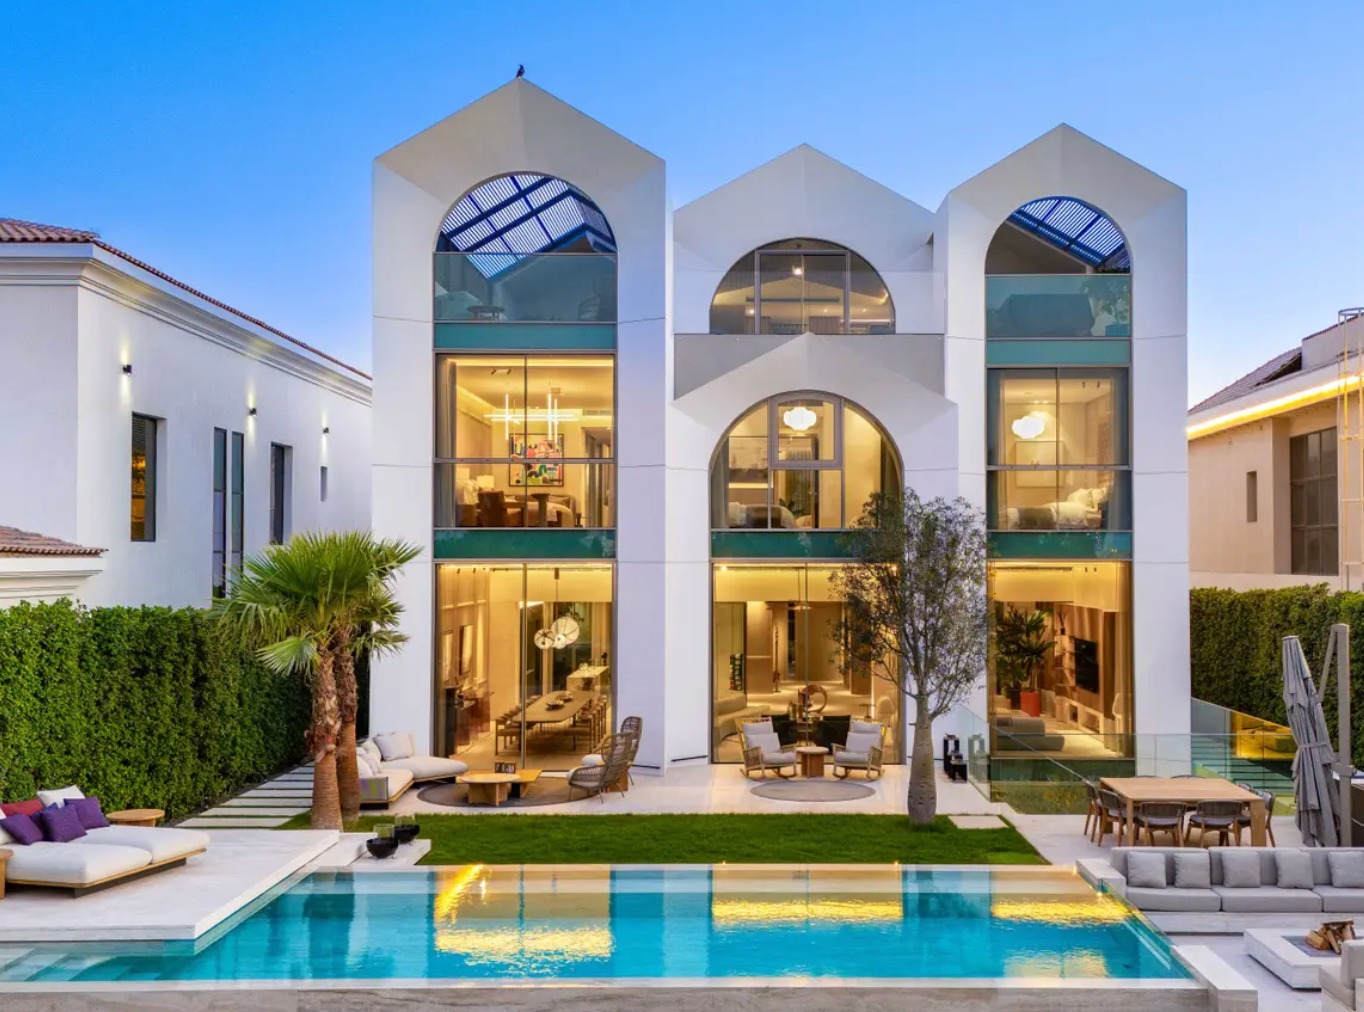
Jumeirah Golf Estates appeals to buyers seeking gated villa living with a golf-course lifestyle and strong community feel. Dubai Marina and JBR attract buyers looking for urban waterfront living with active street-level amenity. Downtown Dubai is favoured for its landmark address and proximity to DIFC.
Arabian Ranches, Dubai Hills Estate and Emirates Living (Springs, Meadows, Lakes) remain popular for British families prioritising garden space, school catchments and a quieter pace.